What is the Social Casino Market overview, scope, and industry significance?
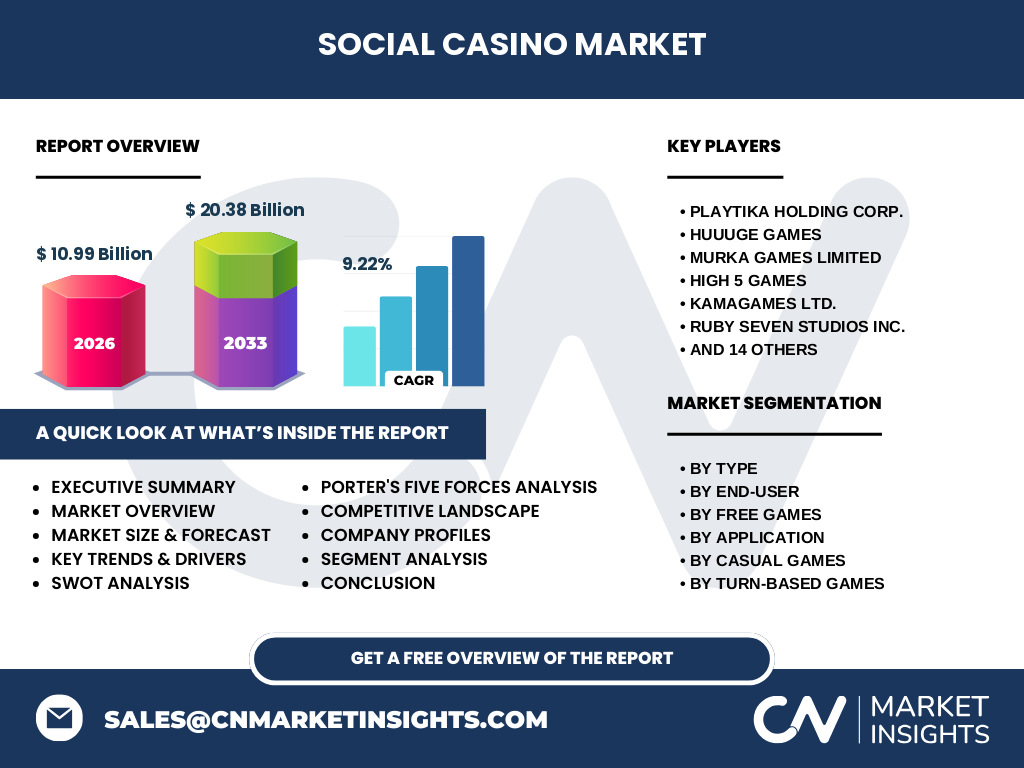
Our analysis indicates the Social Casino Market reaches a valuation of 10.99 Billion in 2026. This sector encompasses virtual gaming environments where players engage in casino-style entertainment without cash payouts. Industry significance stems from its unique monetization model blending free-to-play mechanics with digital currency purchases, driving massive engagement across digital platforms.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The data suggests expansion is propelled by rising smartphone penetration and casual gamer retention. Regulatory scrutiny by bodies like the UK Gambling Commission poses a restraint on monetization mechanics. However, opportunities abound in cross-platform integration, allowing innovators like Playtika Holding Corp. and SciPlay Corporation to capture higher lifetime value.
Emerging Trends and Growth Patterns in Social Casino
The industry witnesses a decisive shift toward hybrid free-to-play models incorporating skill-based elements. Social Casino Market industry trends highlight deeper social integration, allowing users to gift virtual currency and compete on global leaderboards, directly boosting daily active users for firms such as KamaGames Ltd. and Murka Games Limited.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic lockdowns triggered an unprecedented surge in digital leisure, accelerating user acquisition for the Social Casino Market. As physical venues closed, mobile platforms absorbed displaced gamblers. Recovery has stabilized into sustainable organic growth, rewarding companies that optimized user retention loops during the peak anomaly period.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately high, dominated by established conglomerates like Aristocrat Leisure Limited through its Pixel United division, alongside Playtika Holding Corp. and Huuuge Games. Strategic dynamics revolve around aggressive user acquisition campaigns, portfolio diversification into casual puzzles, and data-driven live-ops management to maximize player monetization.
Executive Summary of the Social Casino Market
Our research confirms the Social Casino Market is poised for robust expansion, projecting a valuation of 20.38 Billion by 2033 at a CAGR of 9.22% from 2027. Success requires navigating evolving app store policies and regulatory frameworks while capitalizing on mobile gaming adoption in emerging economic territories.
Market Forecast from 2027 to 2033
Based on our econometric models, the Social Casino Market market size will scale from 10.99 Billion in 2026 to reach 20.38 Billion by 2033. This trajectory represents a steady 9.22% CAGR, driven by expanding mobile infrastructure, optimized monetization, and rising average revenue per paying user across core demographics.
Segmentation Analysis Across Categories and End-Users
The Social Casino Market analysis segments offerings By Type into Casual Games, Free Game, and Turn-Based Game. End-User groups comprise the Gaming Population and Mobile Users. Free Games feature Free-To-Play Slots, Free Poker Games, and Free Bingo. Applications span Free-to-Play, Freemium In-App Purchases And Virtual Currency, Subscription-Based Social Casino, and Hybrid Free-to-Play With Optional Monetization.
Regional Market Analysis and Geographic Distribution
Geographic performance shows North America retaining the dominant revenue share due to high disposable incomes and mature smartphone adoption. Meanwhile, the Asia-Pacific region demonstrates the fastest growth trajectory, driven by surging mobile connectivity and a cultural affinity for digital card and board games, closely monitored by regional regulatory watchdogs.
In-Depth Regional Review of Key Markets
North America leads consumption, supported by robust infrastructure deployed by telecom operators and high propensity for microtransactions. Europe follows closely, though navigating stringent advertising standards enforced by local jurisdictions. Emerging markets in Latin America and Southeast Asia show immense potential for freemium slot machines and bingo variations.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct competitive moats. Playtika Holding Corp. leverages proprietary AI-driven live-ops, while PLAYSTUDIOS Inc. integrates loyalty rewards with real-world entertainment brands. Concurrently, Huuuge Games focuses on collaborative club-centric gameplay, and Ruby Seven Studios Inc. partners with land-based casinos to bridge traditional gaming with digital formats.
Porter's Five Forces Analysis
The threat of new entrants is moderate due to high user acquisition costs required to scale in app stores. Bargaining power of buyers is high given abundant free-to-play alternatives. Rivalry is intense among top-tier publishers like SciPlay Corporation and Murka Games Limited, constantly innovating live-ops to retain engaged player bases.
SWOT Analysis of the Industry
Strengths include high user retention and scalable digital delivery. Weaknesses involve heavy reliance on paid acquisition channels. Opportunities lie in expanding hybrid monetization and blockchain-adjacent virtual economies. Threats center on tightening regulatory compliance across the European Union and potential restrictions on loot-box style mechanics.
Value Chain Analysis from Development to End-User
The value chain flows from software development kits and cloud infrastructure providers to game publishers like Tangelo Games and KamaGames Ltd. These publishers distribute titles via major app ecosystems such as Apple App Store and Google Play, ultimately reaching mobile users and the broader gaming population through targeted performance marketing.
Investment Insights and High-Potential Areas
Investors should target developers integrating social mechanics into traditional casual genres, as well as firms optimizing hybrid monetization frameworks. Companies utilizing advanced predictive analytics to curb churn and enhance lifetime value present prime acquisition targets for major conglomerates seeking portfolio diversification.
Conclusion and Key Takeaways for Stakeholders
The Social Casino Market represents a resilient, high-margin digital entertainment sector expanding toward 20.38 Billion by 2033. Stakeholders must balance aggressive user acquisition with proactive regulatory compliance, prioritizing data-driven live-ops and cross-platform accessibility to secure long-term market share.
Research Methodology and Data Triangulation
Baseline estimates for the Social Casino Market are triangulated by combining quantitative trade registry data, primary stakeholder interviews with C-level executives across publishing firms, and secondary macroeconomic indicators from digital commerce databases, ensuring robust, validated market sizing figures.
Scope of the Report and Coverage Parameters
This comprehensive analysis covers global revenue streams across casual, free, and turn-based games from 2026 to 2033. Limitations include fluctuations in regional app store tax policies and shifting definitions of digital gambling legislation across international jurisdictions, which are factored into our variance models.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features strategic studio acquisitions by Stillfront Group and Aristocrat Leisure Limited, alongside product launches emphasizing cross-platform play. Companies are increasingly partnering with entertainment franchises to launch branded slot machines and immersive bingo events, driving engagement across mobile user bases.